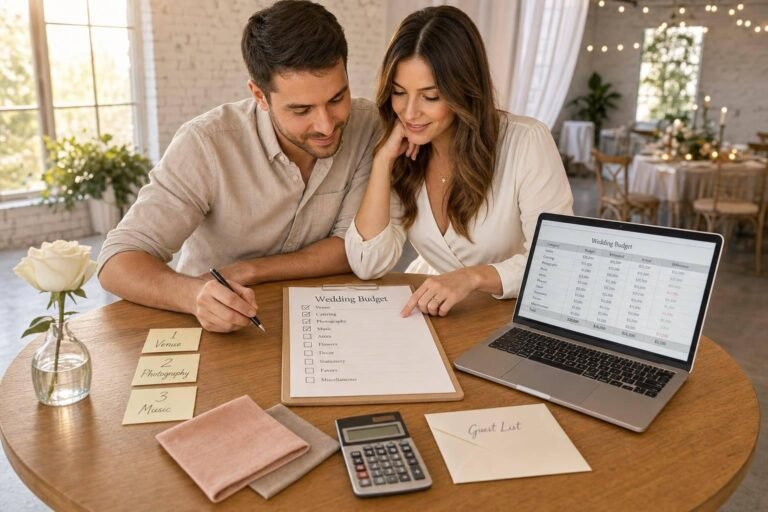
I switched to zero-based budgeting after a year of consistently wondering where my salary went by the 20th of every month. It wasn’t magic, honestly, but it forced a kind of accountability that vague “I’ll save what’s left over” budgeting never did. This zero-based budgeting guide covers exactly how to start.
What Zero-Based Budgeting Actually Means
Every rupee of your income gets assigned a specific purpose — rent, groceries, savings, entertainment — until your income minus your allocations equals zero. Not “spend until it’s zero,” but “assign a job to every rupee until nothing is unaccounted for.”
In short: zero-based budgeting means income minus expenses minus savings equals zero, so nothing floats around unassigned and unaccountable at the end of the month.
Step 1: List Your Total Monthly Income
Include everything — salary, freelance income, rental income, side hustle earnings. Use your actual take-home number, not your gross salary before deductions.
Step 2: List Every Expense Category
- Fixed expenses: rent, EMIs, insurance premiums, subscriptions
- Variable necessities: groceries, utilities, fuel
- Savings and investments: SIPs, emergency fund contributions
- Discretionary: eating out, entertainment, shopping
Nothing gets left in a vague “miscellaneous” bucket — that’s where money quietly leaks.
Step 3: Assign Every Rupee
Starting from your total income, subtract each category one by one until you hit exactly zero. If you end up with money unassigned, put it somewhere intentional — extra savings, debt repayment, or a specific sinking fund — rather than letting it sit loose.
Step 4: Track Actual Spending Against the Plan
This is where most people’s first attempt falls apart. Planning the budget is the easy part; actually logging expenses daily or weekly against it is what makes zero-based budgeting work. A simple notes app or spreadsheet is fine — it doesn’t need to be fancy.
Step 5: Adjust Categories Monthly
Your first month’s budget will probably be wrong in a few places. That’s expected. Zero-based budgeting isn’t a one-time-set-it plan; you revise category amounts each month based on what actually happened versus what you predicted.
[link to related guide on 52-week savings challenge here]
Common Mistakes When Starting Out
- Being unrealistically strict on discretionary categories, leading to abandonment within weeks
- Forgetting irregular expenses like annual insurance premiums or festival spending
- Not building in a small buffer category for the inevitable surprise expense
[link to related guide on best budgeting apps here]
FAQ
Is zero-based budgeting the same as living paycheck to paycheck? No — the “zero” refers to every rupee being assigned a purpose, including savings and investments, not spending everything with nothing saved.
How is this different from the 50/30/20 rule? 50/30/20 uses fixed percentage buckets as a general guideline, while zero-based budgeting requires assigning every single rupee to a specific, named category each month.
Do I need an app for zero-based budgeting? Not necessarily — a spreadsheet works fine, though dedicated budgeting apps can automate tracking and make adjustments easier.
What if my income is irregular, like freelance work? Use your average of the last 3-6 months as a baseline, and treat months above average as opportunities to boost savings categories rather than lifestyle spending.
How long before zero-based budgeting starts feeling easier? Most people find it clicks within 2-3 months, once category estimates stabilize and tracking becomes more of a habit than a chore.
Conclusion
Zero-based budgeting isn’t about restriction for its own sake — it’s about knowing exactly where every rupee is going instead of guessing after the fact. The first month will feel tedious, I won’t pretend otherwise. But by month three, it becomes less of a chore and more of a habit that quietly puts you back in control of your money.