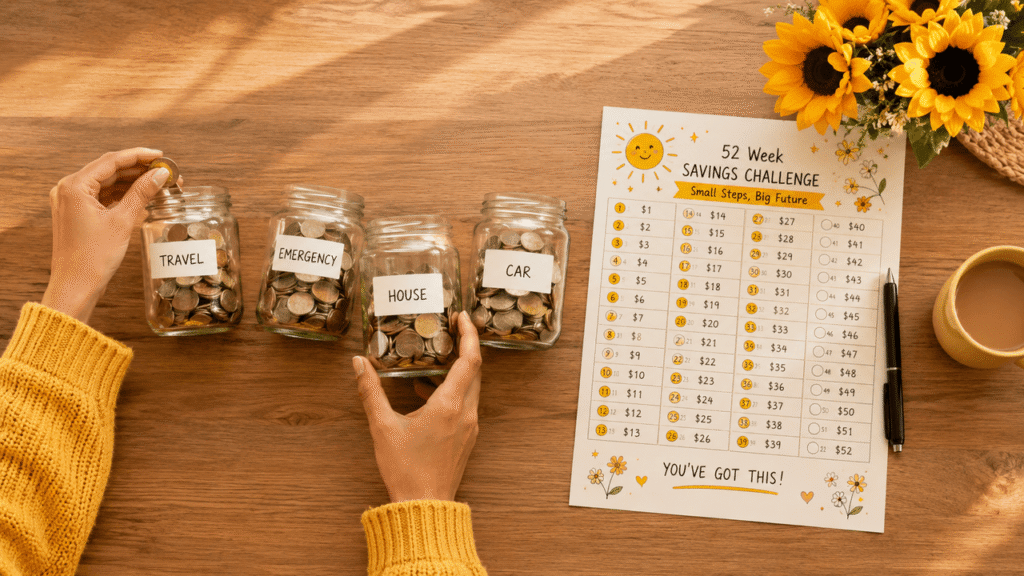
I tried the 52-week savings challenge two years ago after seeing it all over social media, convinced it was too simple to actually work. I made it to week 34 before life got in the way. That experience taught me more about the format’s real strengths and weaknesses than any article promising guaranteed success.
How the 52-Week Savings Challenge Works
The basic version: save an amount equal to the week number, starting with ₹100 in week one, ₹200 in week two, all the way up to ₹5,200 in week 52. By the end of the year, you’ve saved roughly ₹1,37,800.
In short: the 52-week savings challenge builds a habit through gradually increasing weekly amounts, and while the total saved is modest, its real value lies in reinforcing consistency rather than the specific rupee figure.
Why It Works for Some People
- The early weeks are painless, which builds momentum before the harder, later weeks
- Visual trackers (a printable chart, a savings app) create a satisfying sense of progress
- It turns saving into a game rather than a chore, which genuinely helps some people stick with it
Why It Fails for Others
The back half of the challenge is where most people, myself included that year, fall off. Weeks 45-52 require saving ₹4,500-5,200 weekly, which for a lot of monthly-salary earners simply doesn’t align with cash flow, especially if a big expense lands in the same month.
A Reversed Version That Works Better for Many
Some people flip the challenge — starting with the highest amount in week one when motivation is strongest, and decreasing toward smaller amounts by year-end. This front-loads the difficulty when willpower is highest and eases off exactly when motivation typically fades.
Adapting It to Monthly Income Instead of Weekly
If weekly transfers feel disconnected from how you’re actually paid, a monthly version — saving increasing amounts each month instead of week — can align better with salary cycles and reduce the friction of the mismatch.
[link to related guide on how to save money for travel here]
Is the Total Amount Even Meaningful?
₹1,37,800 over a year is a decent amount for a short-term goal, but it’s worth being honest that this challenge alone won’t replace a proper investment or retirement strategy. It works best as a starter habit or as savings toward a specific near-term goal, not a long-term wealth plan.
[link to related guide on zero-based budgeting here]
FAQ
How much do you save total in a 52-week savings challenge? The standard version totals approximately ₹1,37,800 by the end of 52 weeks, assuming no missed weeks.
What happens if I miss a week? Most people either double up the following week or shift the entire schedule forward by a week — either approach works, as long as you get back on track rather than abandoning it.
Is the reversed version better than the standard one? It depends on the person — some do better front-loading difficulty while motivation is high, others prefer easing in gradually. Try whichever matches your typical motivation pattern.
Can this challenge replace regular investing? No, it’s best treated as a short-term savings habit builder or goal-specific fund, not a substitute for long-term investment vehicles like mutual funds or retirement accounts.
Where should I keep the money during the challenge? A separate savings account or recurring deposit works well, keeping it accessible but distinct from your everyday spending money.
Conclusion
The 52-week savings challenge isn’t a financial strategy so much as a habit-building exercise, and there’s real value in that even if the final number isn’t life-changing. Whether you do the standard version, the reversed one, or adapt it monthly, the honest answer is it works as well as your ability to stick with the later, harder weeks. Pick the version that matches your actual motivation pattern, not the one that looks best on Instagram.